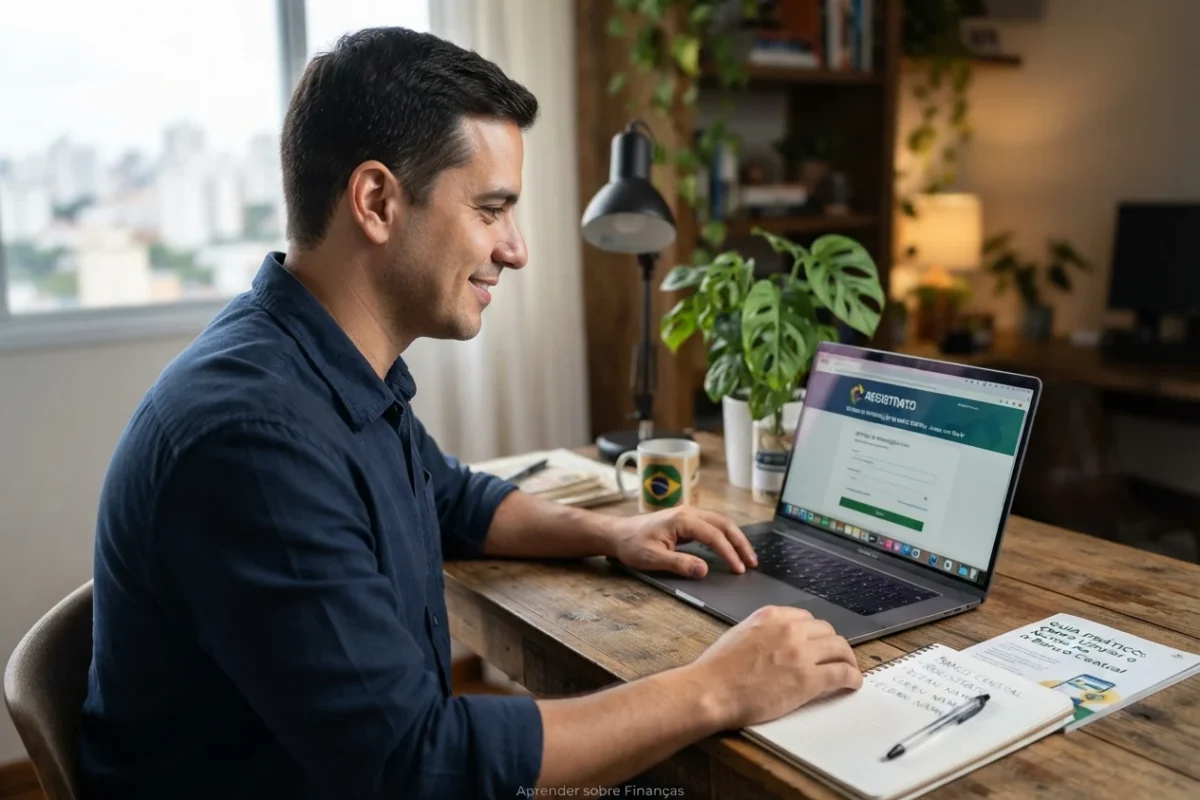
Did you check your financial history and find information you don't recognize? Understanding How to Clear Your Name with the Central Bank Start by distinguishing between a record, an overdue debt, and a possible registration error. Each situation requires a different course of action, and taking the right steps from the start prevents wasted time, scams, and expectations that do not align with the rules of the financial system.
The process involves reviewing the data, identifying the responsible institution, gathering documents, and monitoring the update. In this guide, you’ll learn how to organize each step without confusing the Central Bank with credit protection agencies or with the institution that originated the outstanding debt.
What does it mean to have your name on file with the Central Bank?
Having information on file with the Central Bank does not automatically mean that your credit history is negative. The system compiles data submitted by financial institutions for supervisory purposes and to maintain a record of transactions.
Therefore, to learn how to clear your record with the central bank, you must first find out what type of entry appears there. It could be a credit agreement, a credit limit, a loan, a banking relationship, or other information reported by the institution.
A difference between Serasa and the Central Bank It helps prevent confusion. Serasa acts as a credit bureau, while the Central Bank maintains regulatory systems and reports, such as the SCR, based on information provided by banks and financial institutions.
In our financial literacy tests, we’ve noticed that many readers refer to any entry as a “bad credit record.” This term can refer to a variety of situations: outstanding debt, a closed account that hasn’t been updated yet, or simply incorrect information.
Therefore, understanding how to clear your name with the central bank does not begin with a generic request for removal. It begins with a detailed review of the report and confirmation of the source of the information through official channels.
How to Clear Your Name with the Central Bank
To find out how to clear your name with the central bank, do your research before contacting any company. The report should show which institution is listed, what transaction was reported, and the time period involved.
Next, compare the data with contracts, statements, payment slips, proof of payment, and correspondence you have received. This step helps you distinguish a legitimate outstanding balance from information that is out of date or does not belong to the consumer.
The guide below explains how to clear your name with the central bank without promising immediate removal. Financial regularization and updating a record are related steps, but they do not necessarily occur at the same time.
- See the report: Go to the official channel and see exactly what information appears in your history.
- Check out the source: Check the name of the institution, the type of transaction, the amounts shown, and the reference period.
- Sort the documents: Gather contracts, receipts, case numbers, statements, and messages that will help explain the situation.
- Search for the institution: Request clarification, negotiate, or resolve the outstanding issue when there is a valid financial obligation.
- Request an update: After the issue is resolved, request documented confirmation that the institution will make the necessary notification.
- Check out the results: Check the information again through official channels and keep a record of your interactions.
If the problem is related to a debt listed as delinquent with a credit bureau, see also How to Pay Off Debts Listed with Serasa. This procedure may be supplementary, but it does not replace the review of the Central Bank's report.
How to view and verify your information
An important step in clearing your name with the central bank is to access the report directly through official channels. The Registered, provided by the Central Bank, allows users to view various financial data after completing the required authentication process.
Anyone who wants to understand How to view the SCR report in Registrato You should start by visiting the official website, reviewing the access instructions, and selecting the appropriate report. Login procedures may change, so be sure to check the instructions at the source.
At the conference, note the responsible institution, the type of transaction, the reported period, the recorded amount, and the situation presented. Any detail that differs from the original contract warrants investigation, but does not in itself prove that fraud or an error occurred.
In our case follow-ups, we've noticed that a single screenshot rarely explains the entire situation. Save the full report, note the date of the consultation, and record which details need clarification.
Never provide your password, authentication code, or bank information on pages you receive via text message. To find out how to clear your name with the central bank, please use the Central Bank website typed directly into the browser.
What to Do When There Is an Outstanding Issue
When the report indicates a known outstanding debt, the process for clearing your name with the Central Bank must be handled through the institution that submitted the information. The Central Bank does not function as a debt settlement center.
Contact the bank, finance company, or credit union through official channels. Ask for the contract number, check the current balance, and review the payment terms before accepting any offer.
If an agreement is reached, keep the document that specifies the amount, number of installments, due dates, and method of payment. The receipt must clearly show the transaction in question, especially if you have more than one debt with the same company.
A common question is: Paid-off debt appears in the Central Bank's records? It may still be visible in the history or the reference period, because the report should not be interpreted as a snapshot of restrictions.
Therefore, clearing your record with the central bank may involve two steps: settling the debt with the institution and verifying that subsequent data has been reported correctly. Do not confuse this update with the automatic deletion of your entire history.
It’s also important to ask the institution how the payment will be recorded and to request a receipt number. If the debt is listed in a credit protection registry, check the status directly with that agency. For additional context, read about the effects of having a bad credit history.
How to Dispute Incorrect Information
If you do not recognize the contract or notice a discrepancy in the amount, avoid making hasty decisions. To understand how to clear your name with the central bank, first document the discrepancy and keep records of your interactions.
Gather your identification document, contract, statements, receipts, police report (if applicable), and a copy of the report. Do not send documents to unknown contacts; verify the contact channel through the app, website, or the institution’s contract.
Next, file a request for correction with an objective description. Specify which information is incorrect, why it differs from the documents, and what action you are requesting. Ask for a case number and a written response.
The institution must review the complaint in accordance with its procedures. Consumers can keep track of the process to clear their name with the central bank by recording dates, the names of the representatives they spoke with, the documents they submitted, and the responses they received.
If the response does not resolve the problem, contact the institution's ombudsman and use the available official complaint channels. The Consumidor.gov.br It may be an option in appropriate situations, provided the company is registered.
There is no guarantee that an error will be corrected simply because a request has been filed. Incorrect information requires supporting documentation, review by the responsible institution, and documented follow-up until a final response is provided.
How to Avoid New Financial Problems
Once you've learned how to clear your record with the central bank, maintain a simple monitoring routine. Prevention depends more on consistent record-keeping than on checking your status only when a problem arises.
Once a month, review your statements, bills, active contracts, and automatic payments. Compare what you were charged with what you expected, and quickly question any fees or charges you don’t recognize.
Create a digital folder for each contract, containing the proposal, payment receipts, amendments, and acknowledgments of receipt. Name the files with the date and institution; this makes it easier to find documents months later.
It’s also a good idea to review your budget before taking out a loan. If a monthly payment of R$ 300 eats up almost all of your monthly disposable income, you may end up falling behind on payments even when the interest rate seems attractive.
- Payment schedule: Set up reminders a few days before the due dates and check to make sure the payment was actually processed.
- Contingency reserve: Set aside a monthly amount that fits your budget to reduce your reliance on emergency credit.
- Registration review: Check your data periodically to ensure that closed contracts are displayed with consistent information.
- Organized supporting documents: Keep your receipts until you confirm that the obligation has been written off, settled, or closed.
This routine doesn't automatically improve your credit history, but it reduces the risk of missing deadlines, forgetting payments, or taking too long to notice a discrepancy. In practice, just a few minutes of checking can prevent a more time-consuming investigation later on.
Educational Notice Regarding Financial Information
Report information may serve different purposes, and each case depends on the documents, the responsible institution, and the applicable rules. Therefore, the process of clearing one’s name with the central bank must be handled with attention to detail.
Verify procedures, channels, deadlines, and criteria directly from the official sources of the Central Bank and the institutions involved. Avoid following instructions from websites that promise immediate removal in exchange for payment or the submission of passwords.
If you suspect fraud, seek appropriate guidance and report the facts through official channels. The assessment of a legal professional or consumer advocate may be helpful if the dispute remains unresolved.
The goal is to correct or update information based on evidence, without turning a financial consultation into a cause for alarm. Organization and follow-up are the most reliable tools for navigating each step.
Your next step toward regaining control
Now that you know how to clear your name with the central bank: review the report, identify the source, talk to the institution, and document each step. Start with the official source and proceed without accepting promises of instant results.
If there are other debts in your budget, learn about strategies for reorganizing payments at how to get out of debt. This content is for educational purposes only and does not constitute investment advice. Consult a certified financial advisor before making any decisions.
Frequently Asked Questions About Clearing Your Name with the Central Bank
What does it mean to have your name registered with the Central Bank?
Having a record with the Central Bank does not automatically mean you have a negative credit history. The record may include credit agreements, loans, credit limits, or banking relationships reported by financial institutions. Therefore, it is necessary to review the report and determine whether there are any past-due debts, outdated information, or errors in your records.
How do I clear my name with the central bank when there is incorrect information on file?
First, check the report on the official channel and verify the responsible institution, the transaction, the amounts, and the time period. Next, gather contracts, statements, and receipts; request clarification from the institution; and keep the reference numbers. If there is an error, formally request a correction and follow up on the update.
What is the difference between the Central Bank and Serasa?
Serasa operates as a credit bureau and may record information related to delinquency for risk analysis. The Central Bank maintains regulatory systems, such as the SCR, which are fed by banks and financial institutions. Thus, an entry in the Central Bank’s report does not necessarily mean a negative credit record.
Does paying off a debt immediately remove the record from the Central Bank?
Not necessarily. Making the payment settles the obligation, but the responsible institution still needs to update the information in accordance with the applicable procedures and deadlines. Therefore, keep the receipt, monitor subsequent reports, and contact the bank or financial institution if the information remains incorrect or out of date.
Is it true that any record with the Central Bank results in a bad credit history?
No. The Central Bank collects financial information for supervisory purposes and to maintain a record of transactions, and this does not automatically imply a credit restriction. The record may be legitimate and up to date, or it may indicate an inconsistency. A detailed analysis helps avoid confusing a banking history with a negative credit record or a scam.