Did you know that 70% of Brazilian households Are they facing financial difficulties due to a lack of planning?
This can lead to a range of problems, from the inability to achieve dreams—such as buying a home—to the accumulation of debt.
O Family financial planning It is essential for organizing a family's finances and achieving goals.
When defining clear and achievable goals, you can make better use of your family's resources and ensure a more stable future.
In this article, you'll learn how to involve all family members in the financial planning process and set priorities for the future.
The Importance of Family Financial Planning
Family financial planning isn't just about saving money; it's about building a secure future. Family financial planning serves as a solid foundation that enables you and your family to achieve your goals and overcome financial challenges.
When you start planning your finances, you begin to better understand your family’s expenses and income, which allows for more effective budget management. It is essential for any family, regardless of what stage it is in.
Benefits of Planning Together
Planning together offers several benefits, including greater family unity e better financial decisions. By involving all members, you ensure that everyone is aligned with the financial goals and objectives.
- Improves communication about finances;
- It allows for a more equitable distribution of financial responsibilities;
- It helps identify and eliminate unnecessary expenses.
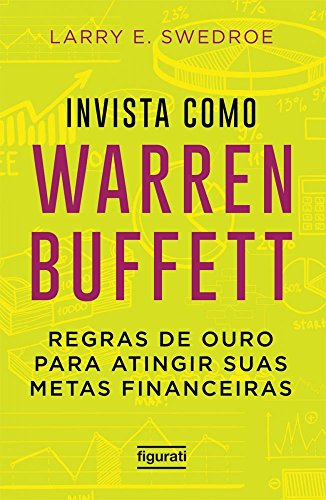
If you want to create the next consumer product that will take the whole world by storm, Steve Jobs would be an ideal role model. If you plan to become a great golfer, you should look to Tiger Woods. Now, if your goals are to outperform other investors and achieve your financial goals in life, what should you do? Think, act, and invest like the best investor there is: Warren Buffett. This book offers a solid and sensible approach to investing based on his advice.
When to Start Family Financial Planning
The best time to start planning your family's finances is now. The sooner you start, the more time you'll have to build a solid financial foundation.
| Family Phase | Recommended Action |
|---|---|
| Childless couple | Set short- and long-term goals |
| Family with young children | Prioritize financial education and saving |
| Teenage children | Teaching Financial Responsibility and Planning for the Future |
Understanding the Family's Current Financial Situation
Understanding the family's current financial situation is the first step toward effective planning. This involves a detailed analysis of the spending e expenses monthly to get a clear picture of where the money is being used.
Mapping Household Expenses
Mapping the household expenses It is essential for understanding how the family budget is being allocated. This includes categorizing expenses into basic needs, conveniences, and luxuries, providing a clear picture of where adjustments can be made.
By tracking your expenses, you'll be able to identify spending patterns and areas where money is being spent unnecessarily. This will help you create a plan to optimize your budget family.
Identifying Expenses That Can Be Eliminated
After mapping out expenses, it is crucial to identify expenses that can be eliminated or reduced without significantly affecting the family's quality of life.
This may include unused subscription services, impulse purchases, or other unnecessary expenses.
By eliminating or reducing these expenses, you'll be able to reallocate the money set aside for more important financial goals, such as savings or investments.
In addition, involving the family in the process of cut Avoiding unnecessary expenses can help foster a culture of financial planning conscious.
- Critically analyze each expense to identify those that do not add value.
- Distinguish between necessary and unnecessary expenses.
- Understand how small cuts can lead to significant savings.
How to Set Family Financial Goals and Achieve Them
Setting financial goals as a family helps create a clear path to financial success. By setting clear and achievable goals, you can focus your efforts on achieving financial stability.
Using the SMART Methodology to Set Goals
The SMART methodology is an effective tool for setting financial goals. SMART stands for Specific, Measurable, Attainable, Relevant, and Time-bound. By applying this methodology, you can set clear and achievable goals.
For example, instead of saying “we want to save money,” a SMART goal would be “we want to save R$ 10,000 in 12 months.” This makes the goal specific, measurable, and time-bound.
Setting Short-, Medium-, and Long-Term Goals
It's important to set goals with different time frames. Short-term goals (up to 2 years) might include paying off debts or building an emergency fund.
| Deadline | Examples of Goals |
|---|---|
| Short Term (up to 2 years) | Pay off debts, build an emergency fund |
| Medium Term (2 to 5 years) | Buy a car, finance a trip |
| Long Term (more than 5 years) | Buying a home, planning for retirement |
By setting goals with different time frames, you can create a comprehensive and balanced family financial plan.
Key Examples of Family Financial Goals
Setting clear financial goals is essential to any family's financial success. Financial goals help direct a family's resources effectively, ensuring that everyone is working toward the same objectives.
Short-Term Goals
Short-term goals are those you want to achieve within two years. Examples include planning a family trip or buying a new appliance. These goals help you stay motivated and maintain financial discipline.
Medium-Term Goals
Medium-term goals are those you plan to achieve within 2 to 5 years. Examples include start your own business or invest in a home renovation. These goals require more detailed planning and commitment.
Long-Term Goals
Long-term goals are those you want to achieve in more than 5 years. Examples include pay for their children's college education, leave an inheritance to one's family, or live abroad.
To achieve these goals, it’s crucial to start planning and investing early. You can find more information about family financial planning on our blog.
Creating a Financial Action Plan
Developing an effective financial action plan is essential to turning your financial goals into reality.
With all the information in hand, it's time to get the family together and assess which spending may be cut or reduced, at least temporarily.
Unifying Expense Management
To centralize control of spending, it's essential to have a clear picture of where your money is going. This involves tracking all your expenses, from the essentials to the nonessentials. You can start by creating a budget detailed family history.
Developing a Containment Plan
Draw up a plan containment of spending A realistic approach is crucial. This may include:
- Identify priority areas for cost reduction;
- Set incremental reduction targets for spending;
- Replace expensive habits with more economical alternatives;
- Create a rewards system to celebrate the savings achieved.
For more information on how to manage your personal finances and investments, visit this link.
| Strategy | Description | Benefits |
|---|---|---|
| Cost Reduction | Cutting unnecessary expenses | Immediate savings |
| Family budget | Tracking all expenses | Financial control |
| Cost-Containment Plan | Gradual spending reduction targets | Financial Discipline |
The 50-30-20 Rule for the Family Budget
The 50-30-20 rule is a simple and effective strategy for family financial planning. It helps you set clear financial priorities, ensuring that you’re prepared for the future.
When applying this rule, you allocate 50% of your income to essential needs, such as housing, food, and transportation. Another 30% goes toward discretionary expenses, which include leisure and entertainment.
The remaining 20% is set aside for savings and investments, ensuring a financial reserve for emergencies and future goals.
Practical Application of the Rule
To apply the 50-30-20 rule in your daily life, you should start by identifying your essential and discretionary expenses. Then, adjust your spending to align with the proportions suggested by the rule.
This may involve cutting back on unnecessary expenses and increasing efficiency in areas such as shopping and leisure. In addition, it's important to monitor your finances regularly to make sure you're on the right track.
| Category | Percentage | Examples of Expenses |
|---|---|---|
| Essential Needs | 50% | Housing, food, transportation |
| Discretionary Expenses | 30% | Leisure, entertainment, hobbies |
| Savings and Investments | 20% | Emergency reserve, long-term investments |
Benefits of the 50-30-20 Rule
Applying the 50-30-20 rule offers several benefits for family financial planning. It helps create a healthy balance between enjoying life in the present and building security for the future.
In addition, this strategy can reduce financial stress and family conflicts related to money. By allocating 20% of your income to financial goals, you accelerate your progress toward your medium- and long-term goals.
The 50-30-20 rule also helps build financial discipline without feeling like you're missing out too much. It's an excellent starting point for families who are just beginning their financial planning.
The Role of Each Family Member in Financial Planning
The involvement of every family member is crucial to the success of financial planning. When everyone contributes, the planning becomes more effective and helps achieve financial goals more quickly.
Family financial planning is a beneficial strategy for the entire family, not just the head of the household. It is a long-term approach that can be passed down from generation to generation, becoming a family tradition.
Sharing Financial Responsibilities
Sharing financial responsibilities among family members not only lightens the workload but also teaches everyone about financial management.
Each member may have a specific task, such as managing expenses, monitoring accounts, or planning investments.
This division helps foster a sense of shared responsibility and promotes collaboration.
Involving Children and Adolescents in Financial Education
Involving children and teenagers in financial education is essential for the family's financial future. Introduce basic financial concepts in a fun way It can help children develop financial management skills from an early age.
Practical activities, such as teaching children about saving and spending wisely, can be very effective. In addition, using an allowance as an educational tool can help young people develop financial skills.
Building an Emergency Fund
Having an emergency fund is essential to ensuring your family's financial stability. It allows you to handle unexpected expenses without compromising your family's budget.
How much to save and where to invest
The ideal amount for an emergency fund varies depending on your family’s needs, but it’s generally recommended to set aside 3 to 6 months’ worth of expenses.
It is important to invest this money in a liquid, low-risk investment, such as a savings account or a DI fund.
Some options for investing your emergency fund include:
- Savings
- DI Funds
- Net CDB (Certificate of Deposit)
How to Use the Reserve Consciously
It is crucial to clearly define what constitutes a financial emergency to prevent misuse of the reserve. In addition, it is important to replenish the funds used as soon as possible after the emergency.
To use the reserve responsibly, you should:
- Establish objective criteria for the use of the reserve
- Consider alternatives before making a reservation
- Inform the family about the use of the reserve
Investments to Achieve Family Financial Goals
The key to achieving your family's financial goals is to diversify your investments. This allows you to spread out the risk and increase your chances of success.
Investment Options for Different Goals
To achieve different goals, you can consider various investment options. For example, for short-term goals, you might opt for more liquid, low-risk investments, such as savings accounts or Treasury bonds.
As for long-term goals, investments in actions or real estate funds may be more suitable, as they have the potential for higher returns over time.
Diversifying Sources of Income
In addition to investing, diversifying your sources of income is crucial. This can include rental income, dividends stocks, or even their own business.
Diversifying your income helps ensure that your family has financial security, even in the event of unforeseen circumstances.
Monitoring and Review of Financial Goals
Reviewing your financial plan periodically is essential for adjusting strategies and staying on track. This allows you to identify areas for improvement and make the necessary adjustments to achieve your goals.
Tools for Tracking Progress
There are several tools that can help you track your progress toward your financial goals, including apps for household financial management.
These apps let you track expenses and income and manage your budget effectively. Some popular examples include personal budgeting apps that can be adapted for family use.
By using these tools, you can gain a clear picture of your family’s financial situation and make informed decisions. For more information on financial planning, you can visit this link.
When and How to Review the Plan
It's important to establish a regular routine for reviewing your financial plan. This can be done monthly or quarterly, depending on your family's needs.
During these reviews, you should assess progress toward the goals, identify any deviations, and make any necessary adjustments.
In addition, events such as changes in income or unexpected expenses may require an ad hoc review of your financial plan. Maintaining flexibility and being prepared to adapt your financial plan are crucial to long-term success.
Overcoming Challenges on the Path to Financial Goals
The journey toward achieving family financial goals is full of challenges, but there are strategies for overcoming them. Staying focused and disciplined is key to reaching your financial goals.
If you're just starting to plan your family's finances, it's important to understand that unexpected financial situations can arise at any time. However, with a solid plan and a financial cushion, you can minimize the impact of these events.
Dealing with Financial Setbacks
Financial setbacks are inevitable, but you can prepare for them. An emergency fund is essential for handling unexpected expenses without compromising your financial goals.
Strategies for dealing with unforeseen events:
- Build an emergency fund.
- Prioritize essential expenses.
- Adjust your budget as needed.
Maintaining Discipline and Focus
Maintaining discipline and focus is crucial to achieving your financial goals. You can use psychological techniques to stay motivated and create systems that turn financial discipline into a habit.
| Strategies | Benefits |
|---|---|
| Set clear goals | Focus your efforts on the goal |
| Create an action plan | Organize the necessary tasks |
| Track progress | Allows for adjustments and keeps you motivated |
Conclusion
Family financial planning is a strategy that goes beyond simple financial organization; it is a journey that brings the family together around shared goals.
Throughout this article, you have learned that the Family financial planning It is not only necessary for organizing fixed and passive finances, but also serves to ensure compliance with the objectives together.
This is a strategy that benefits the entire family, not just for the head of the household.
You now understand that defining financial targets Clear and realistic goals are essential for guiding the family’s efforts and maintaining motivation.
In addition, he understood the importance of assessing the current financial situation before establishing objectives the future and learned about the SMART methodology for setting achievable goals.
With these tools and skills, you're ready to start or improve your financial planning family, strengthening bonds and fostering a healthy financial culture for future generations.
FAQ
Q: What is the first step in setting family financial goals?
A: The first step is to understand your family's current financial situation by tracking all your expenses and identifying areas where you can save money.
Q: How can I involve my children in financial planning?
A: You can start by teaching them basic financial concepts and involving them in discussions about budgeting and saving, making them part of the decision-making process.
Q: What is the 50-30-20 rule, and how can it help with family budgeting?
A: The rule suggests allocating 50% of your income to basic needs, 30% to wants, and 20% to savings and debt, helping you maintain a healthy balance in your budget.
Q: How do I choose the best investments for my family's financial goals?
A: It is important to consider the time horizon of your goals, your family’s risk profile, and to diversify your investments in order to maximize returns and minimize risks.
Q: What should you do when unexpected financial problems arise?
A: Having an emergency fund is crucial. In addition, staying calm and reassessing your budget to adjust to the new circumstances is essential.
Q: How can I stay disciplined and focused on my financial goals?
A: Setting clear and achievable goals, regularly tracking progress, and celebrating successes helps maintain motivation and discipline.
Q: What are the main benefits of planning your family's finances?
A: Planning together fosters unity, helps prevent financial conflicts, and increases the chances of achieving financial goals.
Q: How can you review and adjust your financial plan over time?
A: Regularly reviewing your budget and goals, and adjusting them as needed, helps ensure that you're on track to achieve your objectives.