How can a family invest every month if it doesn't yet know how much of its income is already committed? The Family financial planning It starts with this approach: turning inputs and outputs into decisions that are transparent, shared, and aligned with the reality of the home.
Throughout this guide, you'll learn how to budget, set goals, build an emergency fund, and choose investments. The goal isn't to promise automatic results, but to offer a practical method for managing your money and reducing impulsive decisions.
What Is Family Financial Planning?
Family financial planning is the process of organizing the income, expenses, and goals of everyone involved in the finance in the household. This includes spouses, adult children, or other residents.
In practice, family financial planning helps you determine your net income, track expenses, align priorities, avoid making decisions in isolation, and allocate money toward specific goals.
A simple classification makes diagnosis easier. Essential expenses include housing, food, health care, and basic transportation. Variable expenses fluctuate in amount, such as leisure activities and grocery shopping. One-time expenses, on the other hand, occur at specific times, such as taxes, school tuition, and maintenance.
Consider a family that receives a net income of R$ 6,000 per month. If R$ 4,800 is already allocated to bills, installments, and basic living expenses, that leaves R$ 1,200 for goals, savings, and discretionary spending. Investing without knowing this limit can lead to premature redemptions.
In our tests with household budgets, we realized that the main initial benefit doesn’t come from cutting everything, but from making choices visible. This way, family financial planning becomes an objective conversation, not a personal reproach.
Analysis of Household Income and Expenses
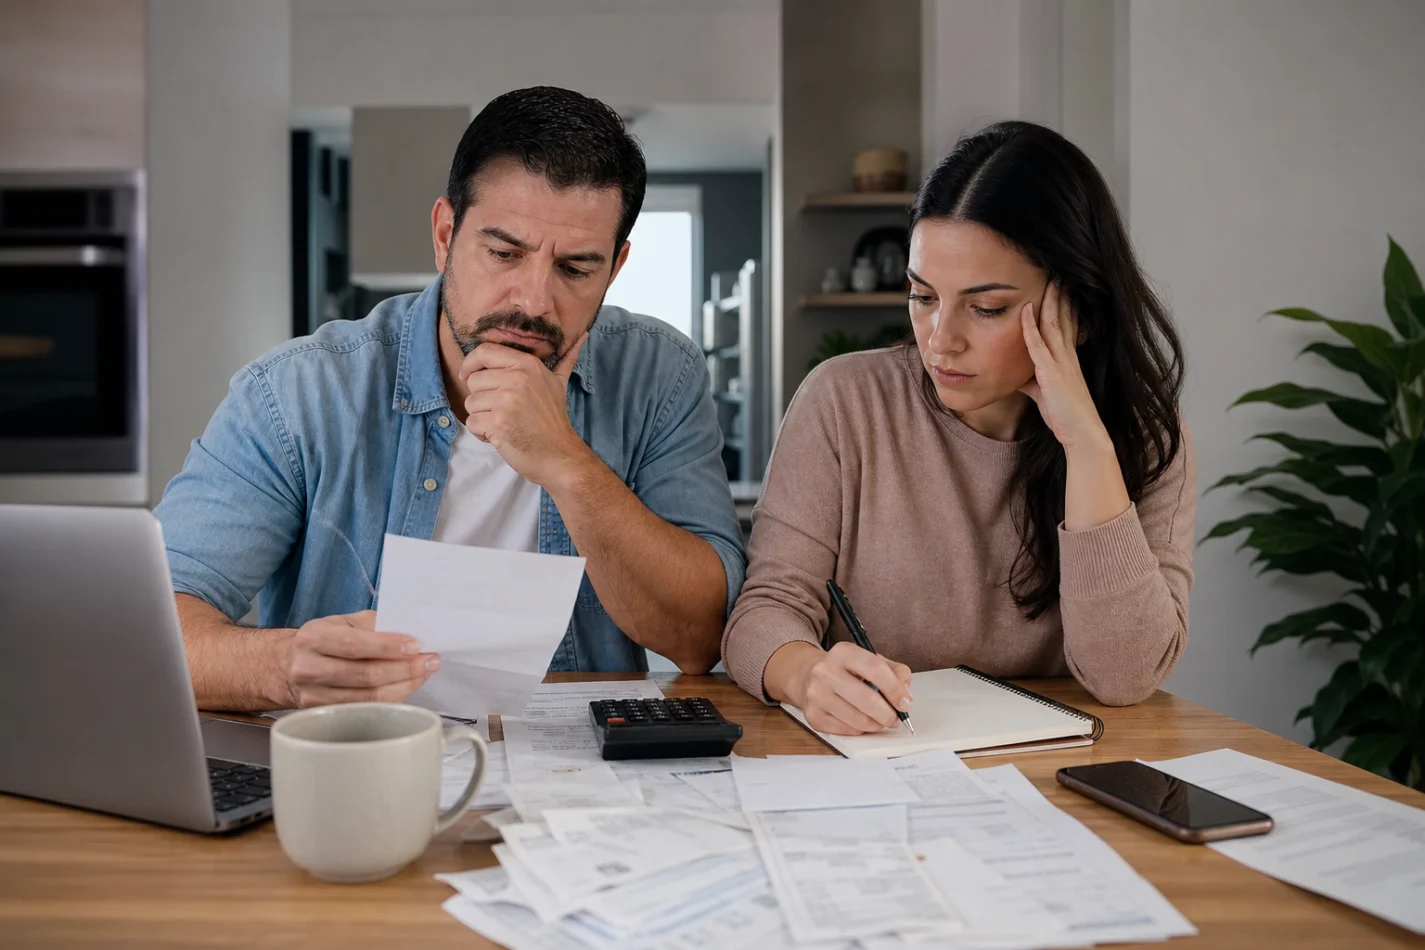
Start by listing your salary, retirement benefits, rent received, side jobs, and other sources of income. Separate predictable income from unpredictable income: your salary can be included in your base budget, while a bonus should be treated as a possibility.
Next, record your rent or mortgage, condo fees, basic bills, food, transportation, education, healthcare, subscriptions, insurance, and debts. Use actual amounts from the last three months, making sure to include small purchases and bank fees as well.
One Household Expenses Spreadsheet It can be simple. An app, a notebook, or a digital file will work, as long as everyone records their expenses and keeps the categories consistent.
To make a useful diagnosis, follow this short sequence and repeat the process monthly:
- Collect recipes: List your net income, benefits, and extra income, distinguishing between recurring and non-recurring sources.
- Extract the expenses: View statements, invoices, payment slips, and receipts from the past few months.
- Classify expenses: Break down fixed, variable, and contingent costs, as well as debts and goals.
- Finding leaks: Look for forgotten subscriptions, fees, purchases made in installments, and recurring charges.
- Check with your family: Check the figures with those involved in financial decisions.
Imagine a net income of R$ 4,500. An initial budget could set aside R$ 2,100 for fixed costs, R$ 900 for variable expenses, R$ 600 for debt payments, R$ 600 for goals, and R$ 300 for occasional expenses.
This family financial plan doesn't have to be down to the last cent in the first month. It should show whether the categories fit within your income and which choices need to be adjusted before taking on new payments.
To learn about budgeting and financial management, it’s worth consulting the guidelines from financial education of Bank Central.
How to Allocate Expenses and Set Priorities
The division of expenses doesn't have to be split evenly. Family financial planning can take into account income, financial obligations, children, individual debts, and agreements reached among the participants.
One option is to split expenses proportionally based on income. Another is to maintain a joint account for shared expenses and separate accounts for personal expenses. It’s also possible to set fixed contributions, as long as they’re adjusted when income changes.
If one person receives R$ 3,000 and another R$ 2,000, the total income is R$ 5,000. A shared expense of R$ 1,500 can be split 60% to 40%: R$ 900 for the first person and R$ 600 for the second.
To decide what to include in the budget first, use clear criteria:
- Basic protection: Prioritize housing, food, health care, necessary transportation, and education.
- Cost of debt: Pay off high-interest debts first, such as revolving credit card debt and overdrafts.
- Continuity: Set aside funds to prevent greater losses, such as adequate insurance and essential services.
- Reservation: Set aside part of your income for emergencies before increasing discretionary spending.
- Deadline: Compare the urgency of the goal with the impact of postponing or paying for the purchase in installments.
In practice, family financial planning works best when no one has to ask for permission for every small purchase, but everyone sticks to the limits that were agreed upon in advance.
If the couple intends to Save money together, you can set up an automatic transfer after receipt. The agreement must specify the amount, purpose, access rights, and what will happen if income decreases.
Family financial planning should also treat personal expenses with respect. Completely taking away personal autonomy can create conflicts and make it difficult to stick to the plan for many months.
Goals, reserves, and simulations with numbers
A useful goal specifies how much will be needed, when the money will be used, and what monthly contribution fits within your budget. “Saving more” is an intention; “saving R$ 12,000 in 24 months” is a measurable goal.
Family financial planning can organize goals into three categories: paying off debts, protecting your home against unforeseen events, and financing specific plans, such as a trip, a course, a home renovation, or a down payment on a property.
For a goal of R$ 12,000 over 24 months, the calculation—without taking returns into account—is straightforward: R$ 12,000 divided by 24 equals monthly contributions of R$ 500.
When building an emergency fund, consider essential expenses and income stability. A family with stable employment may need a different emergency fund than one that relies on commissions, self-employment, or a single source of income.
If the goal is to save R$ 18,000 by contributing R$ 750 per month, it will take 24 months—again, without taking income into account. The calculation shows the effort required, but does not guarantee the final net result.
Interest rates, inflation, taxes, fees, and changes in contributions affect projections. Therefore, family financial planning should treat these figures as estimates and adjust the plan when circumstances change.
In our follow-ups, goals with defined time frames and amounts are easier to adjust. If a monthly payment of R$ 500 doesn't work, the family can extend the term to 30 months, increase the payment during better months, or lower the target amount.
When paying off a debt, compare the cost of interest with the potential return on an investment. In many cases, eliminating an expensive debt offers greater predictability than seeking returns on an investment subject to fluctuations.
You shouldn't keep savings in just any investment simply because it offers a higher return. The money needs to be available when an emergency arises, even if that limits the expected return.
Where to Invest Your Extra Money
Investing comes after managing your budget, negotiating expensive debts, and building up your savings. Family financial planning should match each investment product to its time horizon, the required liquidity, and your tolerance for loss.
Family financial planning doesn't have to start with a lot of assets. Choosing a few straightforward products can make it easier to keep track of things and reduce impulsive decisions. See also the explanations in the CVM about market risks and products.
The table below compares specific options. Before investing, check the issuer, rules, costs, taxation, and redemption terms for the current offering.
| Product | Objective | Risk | Liquidity | Key Feature |
|---|---|---|---|---|
| Selic Treasury | Reservations and Short-Term Rentals | Low market risk, with possible fluctuations | Daily rate on business days, in accordance with operational rules | Floating-rate government security linked to the Selic rate |
| CDB with daily liquidity | Reserves and Short-Term Objectives | The bank's credit risk, covered by the FGC in accordance with the rules | Per diem, when provided for in the contract | Fixed-income securities issued by banks, with a fixed rate of return |
| LCI | Objectives consistent with the agreed-upon timeline | Issuer credit risk | It may have a shortage or limited liquidity | Fixed-income investments linked to the real estate sector; check current tax rules and terms |
| FII | Exposure to the real estate market | Market fluctuations and risks associated with real estate or receivables | Trading on the stock exchange, with no guarantee of an immediate sale | Real estate fund shares; distributed income may be subject to specific rules |
| Bitcoin | Long-term investment for those willing to accept high volatility | High risk of price fluctuations | Trading depends on the platform and the market | A crypto asset with no guaranteed return or protection against losses |
Selic Treasury bonds can provide emergency funds, while a CDB with daily liquidity offers an alternative for fixed-income banking investments. For both, be sure to check the term, the financial institution, the costs, and the protection rules.
An LCI may make sense for a goal with a time frame that allows for a potential grace period. Don’t treat the tax exemption applicable to the product as a sufficient reason: liquidity and net return also matter.
FIIs are suitable for investors who are willing to accept market fluctuations and seek exposure to the real estate market. Distributed income complies with legal requirements, and capital gains from the sale of shares are subject to a 20% tax rate.
Bitcoin should account for only a portion that is consistent with your family’s ability to withstand significant losses. Do not use money from your emergency fund or a related account in an attempt to make a profit.
Family financial planning must take into account risk profile and time horizon. Past performance is no guarantee of future returns, and investment choices should be reassessed as the goal draws nearer.
To find information about government securities, use the Treasury Direct and check the current conditions before applying.
Plan Review and Next Steps
Set aside some time each month to compare your budget with your actual spending. Check which categories went over budget, which expenses decreased, and whether your contributions were made in the expected amounts.
Family financial planning should be reviewed more thoroughly when there is a change in income, the birth of a child, a job change, new debt, or a change in goals.
If the grocery bill has exceeded the limit, investigate the cause before simply cutting it off. Perhaps the category is underestimated, or a one-time expense was recorded in the wrong place.
Update goals without turning monitoring into punishment. Transparency among participants increases the likelihood of sticking to the agreement and prevents one person from having to shoulder decisions that affect the entire household on their own.
To learn more about family organization, check out this guide on involve everyone, see the Steps Toward Goals and learn about guidelines for invest in the future.
Family financial planning is most effective when you start small: track your expenses, set priorities, automate a goal, and review the numbers next month. Consistency comes from realistic decisions, not from a perfect budget.
A financial agreement for the next phase
Start today by gathering your statements, defining responsibilities, and setting a measurable goal. A clear family financial plan can show you where to make adjustments and how much to set aside for savings, goals, and investments.
Use the recommended supplementary guides, talk to everyone involved, and review the plan monthly. This content is for educational purposes only and does not constitute investment advice. Consult a certified financial advisor before making any decisions.
Frequently Asked Questions About Family Financial Planning
What is family financial planning, and why is it important?
Family financial planning is the joint organization of a household’s income, expenses, and goals. It helps families understand their net income, identify financial obligations, align priorities among household members, and reduce impulsive decisions. With clear information, families can better allocate their money toward financial security, goals, and investments.
How do you actually get started with family financial planning?
List your wages, benefits, pensions, and other sources of income, separating predictable income from unpredictable income. Then, review your bank statements, bills, and receipts from the last three months to track housing, food, transportation, healthcare, education, debts, and subscriptions. Categorize your expenses and repeat this analysis monthly to track changes.
What is the difference between fixed, variable, and contingent expenses?
Fixed expenses tend to remain at similar levels, such as rent or loan payments. Variable expenses fluctuate, such as groceries and leisure activities. One-time expenses, on the other hand, arise during specific periods, including taxes, school tuition, and maintenance. Distinguishing between these categories helps you anticipate financial obligations and prevents seasonal expenses from catching you off guard.
Is it possible to invest every month before setting a budget?
Investing without knowing how much of your income is already committed can lead to premature withdrawals and throw your budget off track. First, determine how much money you have available after essential expenses, debts, and planned expenditures. Next, set aside an emergency fund and choose investments that align with your family’s goals and time horizon.
Does family financial planning require cutting out all non-essential expenses?
Not necessarily. A common myth is the belief that organizing your finances means giving up leisure and spending. The main initial benefit comes from making choices transparent, identifying areas of waste, and aligning priorities. With clear categories, a family can keep its spending flexible within a limit that fits its reality.